

-
TL;DR: The U.S. and Lockheed Martin finalized a 10-year framework for at least 850 F-35s, plus spare parts, upgrades and sustainment, with Lockheed committing at least $7 billion. The plan sets a minimum of 85 U.S. aircraft annually but remains subject to congressional funding, with prices and delivery schedules unresolved, as upgrade delays, parts shortages and declining mission-capable rates continue to affect the fleet.
Ten-Year F-35 Framework
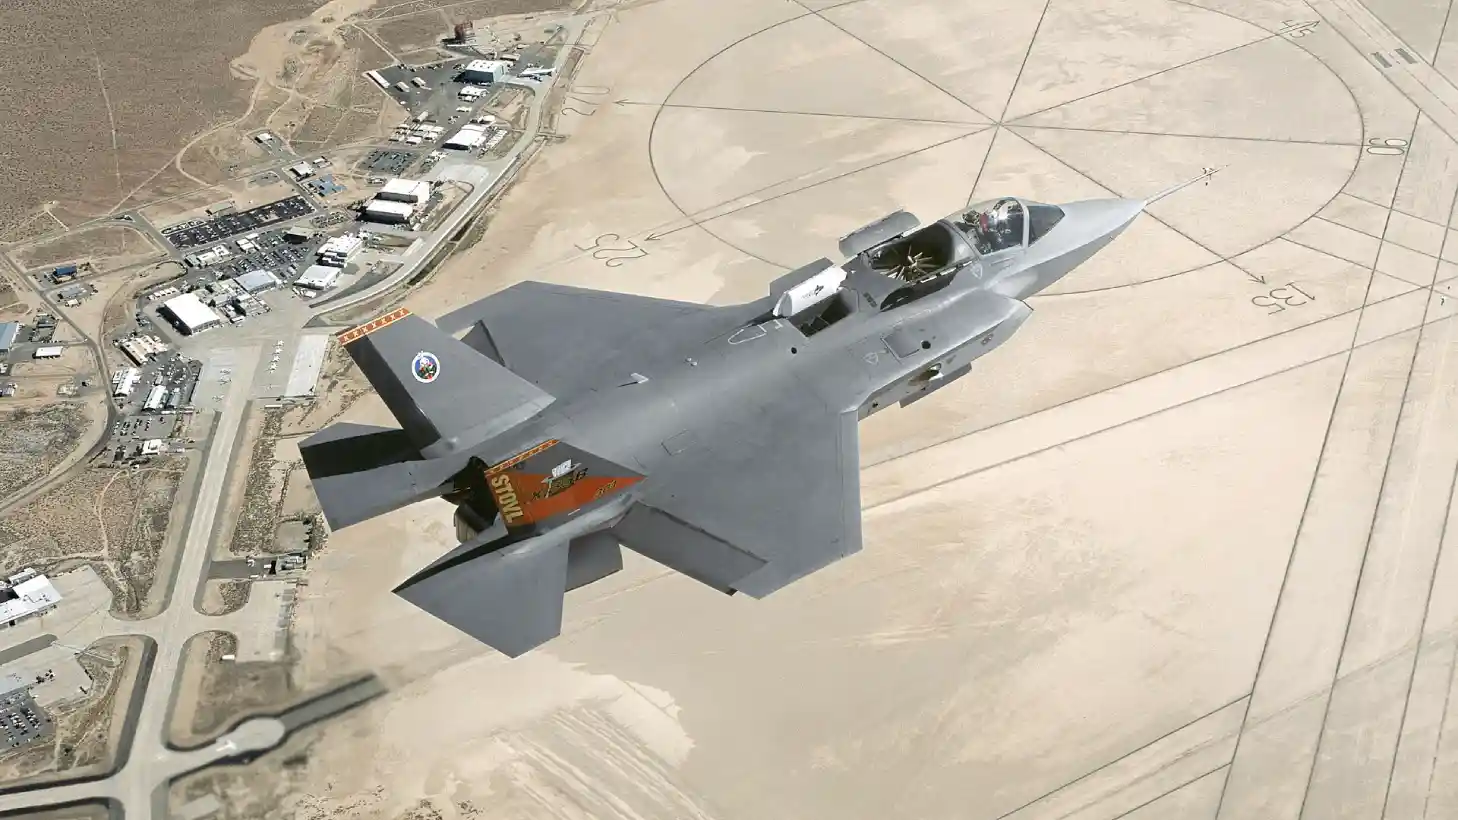
The U.S. Department of War and Lockheed Martin finalized a 10-year framework agreement on Oct. 22, 2026, covering at least 850 F-35 Lightning II fighters for the U.S. military. The plan spans production Lots 21 through 30 and includes initial spare parts, modification kits, and sustainment of the global F-35 fleet.
Lockheed Martin will self-fund at least $7 billion in initiatives supporting the program. Execution remains subject to congressional authorization and appropriations, while aircraft pricing and delivery schedules have not been established.
The agreement provides a minimum U.S. procurement level of 85 aircraft annually. Overall manufacturing is expected to remain at 156 aircraft per year, potentially totaling 1,560 over the decade if production is uninterrupted and all available positions are filled. That would leave capacity for 710 international orders or additional U.S. purchases.
Production and Deliveries
Annual F-35 deliveries rose from nine aircraft in 2011 to 134 in 2019. Lockheed Martin subsequently delivered 120 in 2020, 142 in 2021, 141 in 2022, 98 in 2023 and 110 in 2024.
Deliveries reached a record 191 in 2025, but about 93 of those aircraft had been built earlier and held pending acceptance. This backlog means the figure did not represent the program’s regular annual manufacturing output.
Lockheed Martin delivered 94 aircraft through September 2026, down from 143 during the same period of 2025. Total production deliveries reached 1,387 aircraft by Sept. 27, 2026.
Manufacturing involves Lockheed Martin’s Fort Worth assembly plant, Northrop Grumman center fuselages, BAE Systems components, Pratt & Whitney F135 engines, and final assembly facilities in Cameri, Italy, and Nagoya, Japan.
Upgrade Delays and Readiness
The principal recent disruption involved the Technology Refresh 3 upgrade, which introduces processors, memory, and cockpit displays providing approximately 25 times the computing capability of the previous architecture. The Pentagon suspended acceptance of newly built TR-3 aircraft in July 2023 because of software instability, allowing more than 100 fighters to accumulate.
Deliveries resumed in July 2024 under an interim configuration. Stored aircraft required maintenance, software updates, and four inspection stages before acceptance. TR-3 also underpins planned Block 4 improvements to sensors, electronic warfare systems, weapons integration and cooling.
The framework links production more directly with sustainment as U.S. fleet availability has declined. Mission-capable rates fell from 67% in fiscal 2021 to 44% in fiscal 2025, while fully mission-capable rates dropped from 38% to 25%. Spare-parts shortages, depot backlogs, and repair delays contributed to the agreement’s emphasis on replacement components, modification kits, and inventory management.
Three F-35 Variants
The conventional F-35A uses the F135-PW-100 engine. The short-takeoff and vertical-landing F-35B combines an F135-PW-600 engine with a lift fan and swiveling exhaust nozzle. The carrier-based F-35C has larger folding wings, reinforced landing gear, and arresting equipment.
The Marine Corps declared initial operational capability for the F-35B in 2015, followed by the Air Force’s F-35A in 2016 and the Navy’s F-35C in 2019. Because the variants share major computing systems, software problems can affect deliveries across all three.
Chinese Production Context
The agreement comes as China expands production of the J-20 and develops the carrier-capable J-35. Estimated J-20 output increased from about 20 annually in 2020 to 100–120 by late 2025, while estimates placed its inventory at 300 by mid-2025. No verified annual production rate is available for the J-35.
F-35 production is divided among three U.S. services and international customers, while Chinese aircraft are primarily assigned within the Indo-Pacific. Operational strength also depends on deployment locations, airfield and carrier access, tanker support, weapons stocks, maintenance capacity, and sortie generation rather than worldwide inventory totals alone.
Recommended Comments